Is the Weak U.S. Housing Market a Problem for the Economy?
Housing is a fundamental part of the American dream—whether it’s for a young person aspiring to buy their first home, or for an older American whose home represents decades of accumulated wealth, financial security, and memories.
The importance of homeownership isn’t just a theoretical idea. A June 2026 Bank of America study found that 90% of respondents viewed a home as a valuable investment, while 94% believed homeownership provides stability.1 The financial significance is also substantial. According to a Census Bureau report released in July, home equity accounted for 31.3% of aggregate household wealth in 2024, excluding the wealthiest 1% of households. Retirement accounts accounted for another 35%.2
Given these figures, it is understandable that high interest rates (over 7% on a 30-year fixed as I write) and low inventories can make readers worry about the state of the housing market—and by extension, the economy.
This is where it makes sense to separate how Americans tend to think and ‘feel’ about the housing market, versus how much the housing market actually impacts the broad economy.
Allow me to start with a hypothetical. When an existing home sells for $400,000, for example, that entire amount does not count as new economic output, since the property already exists. Certain services associated with the transaction, such as real estate commissions, contribute to GDP, but the home’s purchase price largely represents a transfer of ownership.
New construction, residential improvements, and related investment activity have a more direct impact on economic growth. These expenditures are measured primarily through residential fixed investment, which accounted for approximately 3.6% of U.S. GDP in the second quarter of 2026 (see chart below).
U.S. Residential Fixed Investment / U.S. GDP
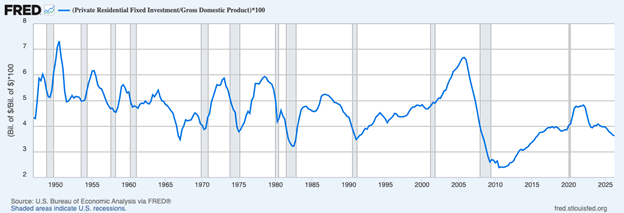
As seen on the chart above, housing’s share of total U.S. economic output has been on something of a steady decline over the past 70+ years. Case in point: in Q1 2026, residential fixed investment subtracted 0.29 percentage point from GDP growth, yet the overall economy expanded at a 2.5% annualized rate. In Q2 2026, residential investment added 0.10 percentage point to growth, while real GDP increased 2.2%.
To be fair, housing has a wider economic footprint than just residential fixed investment. Spending on housing services, including rental payments and the estimated rental value of owner-occupied homes, generally contributes another roughly 12% of GDP.5 That activity is considerably more stable than home sales and new construction, however, since people continue to occupy their homes regardless of how many properties change hands.
I also want to be fair in giving weight to second-order effects of a middling housing market. Weaker construction can weigh on employment, building materials, furniture purchases, and other housing-related industries. Falling home values can also affect household confidence and spending, while more severe problems in housing finance can spread through the banking system (as I’m sure every reader remembers well).
These are risks worth monitoring, particularly if housing weakness begins to coincide with tighter credit conditions or a broader deterioration in employment and consumer spending.
But the latest economic figures send the opposite message.
Bottom Line for Investors
The Federal Reserve held its benchmark interest rate steady at its meeting this past week, but readers should understand that whatever decision emerges from the Fed is not likely to directly impact mortgage rates. Remember, the Fed has its most direct influence over short-term interest rates, while longer-term borrowing costs, including 30-year mortgage rates, tend to reflect expectations for inflation, economic growth, and future monetary policy. Mortgage rates also incorporate additional financing risks and costs.
Fed decisions aside, I think the broader lesson here is to keep housing’s challenges in perspective. High borrowing costs and low housing inventory have meaningful consequences for Americans—both young and old—making major financial decisions. I don’t want to minimize that. But from an investor’s perspective, we should be careful about interpreting a difficult housing market as a canary in the coal mine for the entire economy or stock market. It’s just not as impactful as many believe it to be.
Disclosure
2 U.S. Census Bureau. July 15, 2026. “Wealth of Households: 2024.”
3 FRED, Federal Reserve Bank of St. Louis. September 30, 2026. “Private Residential Fixed Investment (PRFI).”
4 Bureau of Economic Analysis. October 29, 2026. “National Income and Product Accounts.”
DISCLOSURE
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.
Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.
This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.
Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.
Certain economic and market information contained herein has been obtained from published sources prepared by other parties. Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable. Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.