Stocks have been volatile in November, with a sharp selloff after the midterms followed by a broad-based rally that saw 423 S&P 500 stocks finish higher in one session. This kind of choppiness usually inspires me to step back—not because I’m trying to discern what’s driving the day-to-day swings, but because I want to ensure my thinking keeps a healthy distance from the noise.1
To do that, I like to pull all the focus back to economic fundamentals.
Doing so makes the headlines feel like a distraction. According to the Bureau of Economic Analysis’ first estimate, inflation-adjusted U.S. GDP increased at a 3.4% annualized rate in the third quarter, accelerating from 2.2% in Q2. Without the inflation adjustment, that means the economy expanded at a 5.6% annualized pace in Q3. There’s no spinning this data—it’s solid.1
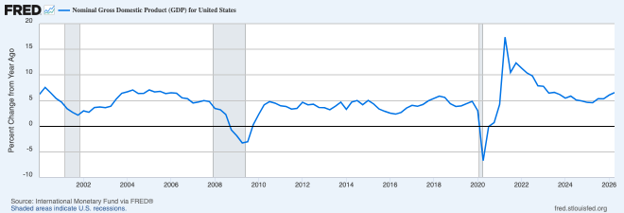
Source: Federal Reserve Bank of St. Louis2
If we look at the component of the GDP data that provides a clear view of demand from households and businesses, which is known as ‘real final sales to private domestic purchasers’, it’s clear that consumer spending and business investment are humming. It rose at a 4.9% annualized rate in Q3, up from 4.6% in the second quarter.
Beyond the Headlines: What’s Driving Stocks?
Daily market swings tell only part of the story. Understanding the economic forces behind them can help investors put volatility in perspective.
Explore our November Stock Market Outlook Report3 for insights on the economy, the stock market, and what they could mean for your portfolio.
Inside, you’ll learn:
- Asset allocation guidelines for today’s market environment
- Expert forecasts for inflation, rates, and economic trends
- Industry tables and rankings to help you spot opportunities
- Buy-side and sell-side consensus insights at a glance
- And much more!
Claim your complimentary copy of the report for a closer look at the fundamentals behind the market’s daily swings and what they could mean for your portfolio in the months ahead.
Download our November Stock Market Outlook Report3
The consumer side of that demand remains strong. Real consumer spending increased at a 3.8% annualized rate for the second consecutive quarter, with spending on goods rising 3% and services spending accelerating to 4.1%. Households were seen purchasing more across a range of necessities and discretionary categories.
When we look at the business investment side of the ledger, this is where we run into the AI trade. Investment in computers and peripheral equipment surged at a 66.7% annualized rate in Q3, with industrial equipment investment growing 24.7%. Technology and the AI buildout are clearly pulling a lot of weight here, but in aggregate, business investment still increased at a 12.7% annualized rate in Q3. Again, very strong.
I would also argue that there’s broader economic significance to business investment data that can get lost in the discussion about AI. When businesses invest in new equipment, software, facilities, and technology, that spending generates revenue for other companies. It also represents an effort to increase productive capacity, improve efficiency, or position for future demand. Whether every investment ultimately delivers an attractive return remains to be seen, but the economic activity taking place today is no doubt substantial and benefiting other parts of the economy beyond the hyper-scalers.
In October, 15 service industries reported growth (services PMI data), including areas such as transportation, health care, finance, and professional services.4 It follows that U.S. employers added 165,000 jobs in the same month, bringing average monthly job growth over the latest three months to 137,000.
One final piece of fundamental data that makes the case for optimism comes from corporate earnings. According to our colleagues at Zacks Investment Research, the 441 S&P 500 companies that had reported third-quarter results through November 6 generated earnings growth of 24.8% on 13.4% higher revenues. The spending and investment we’re seeing across the economy are translating into higher sales and profits for publicly traded companies. That’s ultimately the ‘bottom line for investors.’
Bottom Line for Investors
One of the most important things I look for in evaluating the U.S. economy is whether growth has a durable foundation. Consumer spending, business investment, employment, and corporate earnings all contribute to that assessment, and my view is that each category is pointing in the right direction.
This fundamental strength doesn’t guarantee strong stock market returns, and valuations and company fundamentals will always matter when evaluating individual investments.
But with private-sector demand growing at nearly 5% annualized and corporate profits continuing to expand, I see good reason for constructive optimism looking into Q4 and 2027.
With that optimism comes the question of where investors go from here. Our November Stock Market Outlook Report3 takes a closer look at the economic and market trends that could shape your next investment decisions.
Inside, you’ll learn:
- Asset allocation guidelines for today’s market environment
- Expert forecasts for inflation, rates, and economic trends
- Industry tables and rankings to help you spot opportunities
- Buy-side and sell-side consensus insights at a glance
- And much more!
Claim your complimentary copy of the report for a closer look at the fundamentals behind the market’s daily swings and what they could mean for your portfolio heading into 2027.
Disclosure
2 FRED, Federal Reserve Bank of St. Louis. September 7, 2026. “Nominal Gross Domestic Product (GDP) for United States.”
3 Zacks Investment Management reserves the right to amend the terms or rescind the free November Stock Market Outlook Report offer at any time and for any reason at its discretion.
4 MSN. 2026. “US services-sector activity expands again in October.”
DISCLOSURE
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.
Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.
This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.
Any projections, targets, or estimates in this report are forward looking statements and are based on the firm’s research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.
Certain economic and market information contained herein has been obtained from published sources prepared by other parties. Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable. Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor’s. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.
The Nasdaq Composite Index measures all Nasdaq domestic and international based common type stocks listed on The Nasdaq Stock Market. To be eligible for inclusion in the Index, the security's U.S. listing must be exclusively on The Nasdaq Stock Market (unless the security was dually listed on another U.S. market prior to January 1, 2004 and has continuously maintained such listing). The security types eligible for the Index include common stocks, ordinary shares, ADRs, shares of beneficial interest or limited partnership interests and tracking stocks. Security types not included in the Index are closed-end funds, convertible debentures, exchange traded funds, preferred stocks, rights, warrants, units and other derivative securities. An investor cannot invest directly in an index.