Today’s Steady Investor takes a closer look at three market stories and their potential impact on investors:
- Housing slump weighs on growth
- Sticky inflation challenges the Fed
- Global growth leans on AI
U.S. Housing Market Slumps to a 16-Year Low – The U.S. housing market continues to struggle, with existing-home sales falling 5.5% in October to an annualized rate of 3.75 million, the lowest level since August 2010. Sales declined 8.8% from a year earlier, as rising mortgage rates (back above 7%) and stubbornly high home prices (the median existing-home price reached $416,700) kept prospective buyers on the sidelines. Meanwhile, the supply of homes available for sale has increased to 5.1 months of inventory, the highest level in more than a decade. While buyers have more negotiating power in this environment, financing costs remain a significant obstacle. Weakness is also spreading to homebuilding. Single-family housing starts fell 4.6% in September, while 43% of homebuilders reported cutting prices in October to attract buyers. For the broad economy, fewer home sales mean less spending on renovations, furniture, appliances, and moving services, while slower construction weighs directly on economic activity. Importantly, however, the current downturn differs from the housing crisis of 2008, with distressed sales accounting for just 2% of October transactions. For investors, housing remains a notable pocket of weakness in an otherwise growing U.S. economy. A sustained recovery will likely require lower mortgage rates.1
Markets Are Changing. Is Your Retirement Plan Ready?
Retirement brings new possibilities and important financial decisions.
From estimating future expenses to planning how your savings will support you, the steps you take today can help you approach retirement with greater confidence.
Our free guide, 8 Steps Towards a Stress-Free Retirement2, covers key considerations for building a retirement strategy that supports your goals, including:
- How to plan for emergencies that can derail your retirement investments
- Why missing just 25 trading days can decimate your returns
- Three ways to generate income during retirement
- Plus, other key steps to help you realize your retirement goals
Want to feel more prepared for whatever retirement brings?
Download 8 Steps Towards a Stress-Free Retirement2 to learn practical steps for building a strategy designed for the long term.
October Inflation Data Reinforce the Fed’s Challenge – U.S. inflation remained stubbornly elevated in October, adding pressure on the Federal Reserve to raise rates at its upcoming December meeting. The Consumer Price Index (CPI) rose 0.4% from September, exceeding economists’ expectations of 0.3%. Core inflation, which excludes volatile food and energy prices, also rose 0.3%, slightly above forecasts.3
CPI (blue line) and Core CPI (green line) are No Longer in a Downward Trend
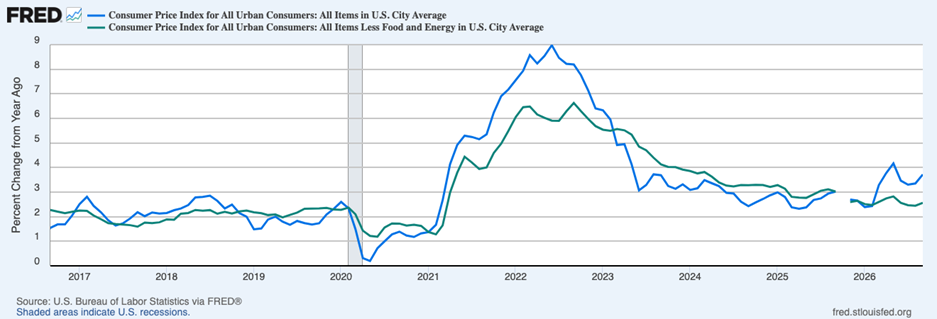
Source: Federal Reserve Bank of St. Louis4
Although the government could not calculate an official year-over-year inflation rate because of missing data from last year’s federal shutdown, the recent trend is concerning. Over the past three months, consumer prices have increased at a 5.7% annualized pace, suggesting inflation remains far from the Fed’s 2% objective. Energy prices moderated somewhat in October, rising just 0.7% after September’s 5.2% increase. However, higher costs appear to be spreading beyond energy. Food prices climbed 0.5%, furniture prices increased 0.7%, and certain electronics experienced notable price increases. These developments suggest inflationary pressures may be becoming more entrenched throughout the economy, which arguably ties the Fed’s hands.
The Global Economy’s Growing Dependence on AI Investment – The artificial intelligence boom has become an increasingly important driver of global economic growth, extending far beyond the United States. Massive spending on data centers, semiconductors, and supporting infrastructure is fueling demand for goods and services produced around the world, providing a meaningful boost to international trade. The numbers illustrate the scale of this impact. According to the World Trade Organization, AI-related goods accounted for nearly half of global merchandise trade growth in the first half of 2026. In Asia, approximately 80% of recent export growth has come from AI-related products. The investment boom is benefiting numerous industries, from chipmakers in Taiwan and South Korea to manufacturers of electrical equipment, cooling systems, and other infrastructure components. But the concentration of growth in a single investment theme also introduces risks. If technology companies eventually scale back their AI spending, the effects could extend well beyond U.S. stock markets. Export-dependent economies could face weaker demand, while suppliers, construction firms, and financial markets could experience additional pressure.5
Put Your Retirement Goals into Focus – You’ve worked hard to build your savings. A thoughtful retirement plan can help you put those savings to work, manage future expenses, and prepare for the unexpected.
Our complimentary report, 8 Steps Towards a Stress-Free Retirement2, explores practical strategies to help you prepare, including:
- How to plan for emergencies that can derail your retirement investments
- Why missing just 25 trading days can decimate your returns
- Three ways to generate income during retirement
- Plus, other key steps to help you realize your retirement goals
Download 8 Steps Towards a Stress-Free Retirement2 to learn practical steps for building a strategy designed for the long term.
Disclosure
2 Zacks Investment Management may amend or rescind the “8 Steps Towards a Stress-Free Retirement” guide for any reason and at ZIM’s discretion.
3 Wall Street Journal. November 10, 2026. “Broad Price Pressures Firm Up Case for Fed Rate Increase in December.”
4 FRED, Federal Reserve Bank of St. Louis. November 10, 2026. “Consumer Price Index for All Urban Consumers: All Items in U.S. City Average (CPIAUCSL).”
5 Wall Street Journal. November 12, 2026. “The Global Economy Looks Vulnerable to an AI Bust.”
DISCLOSURE
Past performance is no guarantee of future results. Inherent in any investment is the potential for loss.
Zacks Investment Management, Inc. is a wholly-owned subsidiary of Zacks Investment Research. Zacks Investment Management is an independent Registered Investment Advisory firm and acts as an investment manager for individuals and institutions. Zacks Investment Research is a provider of earnings data and other financial data to institutions and to individuals.
This material is being provided for informational purposes only and nothing herein constitutes investment, legal, accounting or tax advice, or a recommendation to buy, sell or hold a security. Do not act or rely upon the information and advice given in this publication without seeking the services of competent and professional legal, tax, or accounting counsel. Publication and distribution of this article is not intended to create, and the information contained herein does not constitute, an attorney-client relationship. No recommendation or advice is being given as to whether any investment or strategy is suitable for a particular investor. It should not be assumed that any investments in securities, companies, sectors or markets identified and described were or will be profitable. All information is current as of the date of herein and is subject to change without notice. Any views or opinions expressed may not reflect those of the firm as a whole.
Any projections, targets, or estimates in this report are forward looking statements and are based on the firm's research, analysis, and assumptions. Due to rapidly changing market conditions and the complexity of investment decisions, supplemental information and other sources may be required to make informed investment decisions based on your individual investment objectives and suitability specifications. All expressions of opinions are subject to change without notice. Clients should seek financial advice regarding the appropriateness of investing in any security or investment strategy discussed in this presentation.
Certain economic and market information contained herein has been obtained from published sources prepared by other parties. Zacks Investment Management does not assume any responsibility for the accuracy or completeness of such information. Further, no third party has assumed responsibility for independently verifying the information contained herein and accordingly no such persons make any representations with respect to the accuracy, completeness or reasonableness of the information provided herein. Unless otherwise indicated, market analysis and conclusions are based upon opinions or assumptions that Zacks Investment Management considers to be reasonable. Any investment inherently involves a high degree of risk, beyond any specific risks discussed herein.
The S&P 500 Index is a well-known, unmanaged index of the prices of 500 large-company common stocks, mainly blue-chip stocks, selected by Standard & Poor's. The S&P 500 Index assumes reinvestment of dividends but does not reflect advisory fees. The volatility of the benchmark may be materially different from the individual performance obtained by a specific investor. An investor cannot invest directly in an index.
Questions posed are for demonstrative and informational purposes only and may not reflect the views of current clients or any one individual.